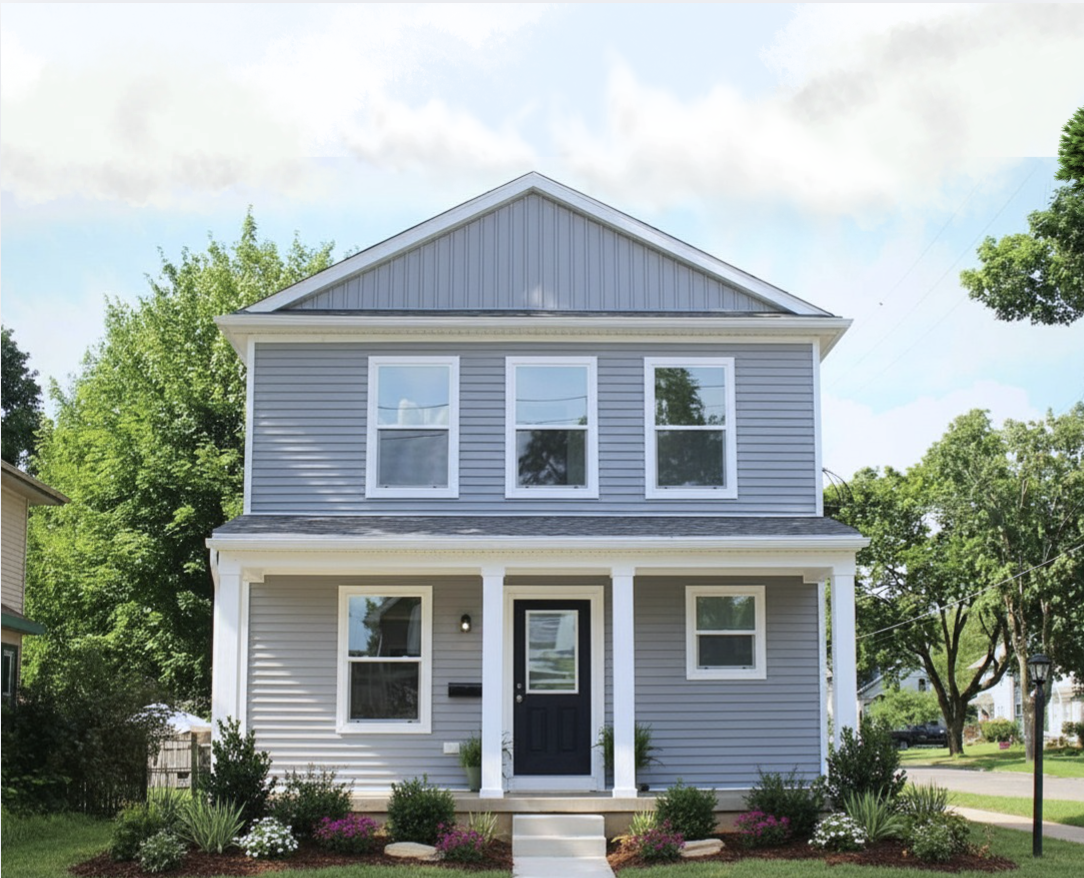
The American dream of homeownership is fading. Bethel Homes wants to change that.
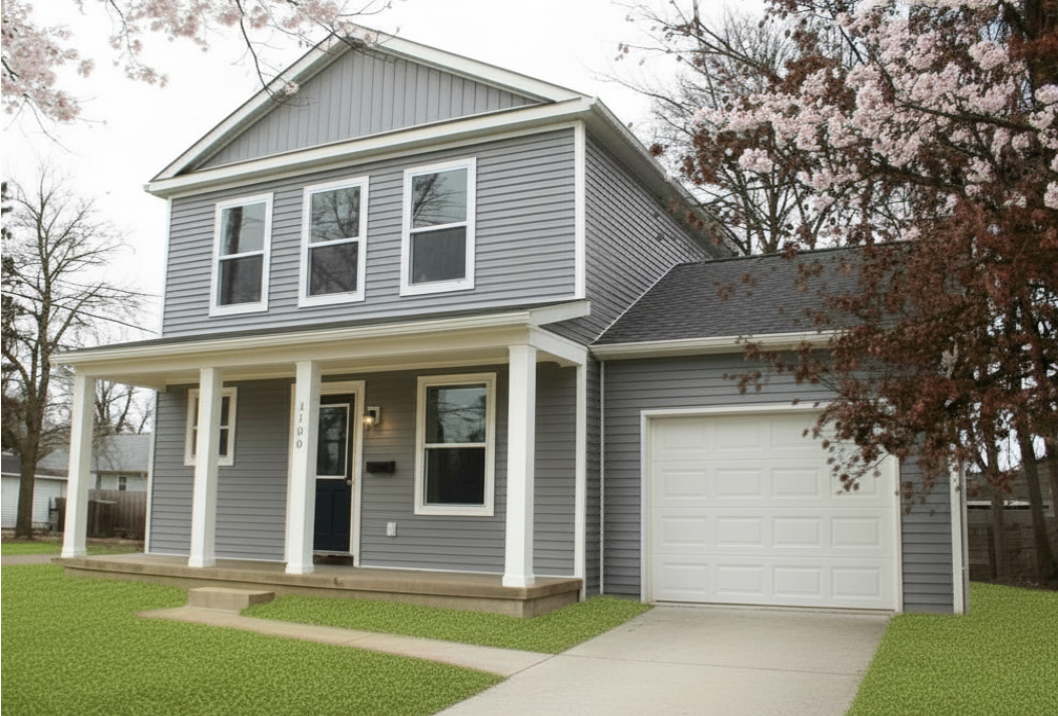
Room to raise a family, built to last
Reserved for our neighbors, and kept attainable for generations
A partnership, not a single hand
Bethel Homes are being developed by Community Catalysts Development Company, a 501(c)3 nonprofit housing developer, and sister nonprofit to Community Catalysts. Other key partnerships include Norfolk Homes, our builder, and partnerships with foundations and philanthropic funders.
Bethel Homes Community Land Trust
A community land trust (CLT) is a housing model in which a nonprofit owns the land and sells the homes on that land to eligible buyers at below-market prices. What makes a CLT distinct is what happens when a homeowner is ready to sell: rather than the home returning to market-rate pricing, a shared-equity agreement keeps it affordable for the next buyer — and the one after that — in perpetuity.
How It Works
At Bethel Homes, we build and rehab high-quality homes, and we raise funds to lower their price to what's attainable for income-qualified households.
Buyers purchase homes at prices significantly below the cost to build or rehab the home and well below market prices. Bethel Homes CLT retains ownership of the land beneath the homes and leases it to the homeowner through an 89-year renewable agreement. Homeowners pay a monthly fee that supports both program administration ($50) and a Replacement Reserve Fund ($50), for a total monthly fee of $100. The Replacement Reserve Fund can help pay for qualifying replacements to your home, such as the roof or windows. It cannot be used for routine maintenance, normal wear and tear, or basic repairs.
Homeowners agree to a resale formula that allows shared appreciation and ensures the home remains affordable to the next income-qualified buyer. This approach fosters stewardship, shared equity, and long-term community benefit for generations to come.
Bethel Homes uses a 75/25 equity sharing model. Upon sale of the home, homeowners earn 25% of the equity accrued since purchase, and the CLT retains 75% of the equity to keep the home attainable for the next income-qualified buyer. In lieu of selling their home, homeowners could choose to pass the ownership of the home to their heirs.
See the Homebuyer Guide for detailed information on the Community Land Trust and the qualification process.
Do I Qualify?
Potential Bethel Homes homebuyers must meet the following criteria:
- Be at least 18 years old
- Be a first-time homeowner, an individual who has not had ownership in a principal residence for 3 years, and/or meet special circumstances, including divorce, ownership of mobile homes, and other criteria as defined by HUD (see FAQ's for the detailed HUD definition)
- Have combined annual income for all adults living in the home, depending on the project designation, at or below 60% of Area Median Income (AMI) and not to exceed 80% of AMI (see below for income detail)
- Have monthly debt payments not exceeding 10% of your gross monthly income
- There is no asset limit
- Currently live or work in Livingston County, or be starting a new job with an employer located in Livingston County
- Have not had any adult in your family living in the home file for bankruptcy in the last 2.5 years
- Have a pre-approval letter for a conventional mortgage or be working on obtaining one (a pre-approval letter will be required as part of the application process)
- Complete a HUD Housing Counseling Session (typically occurs after the application is submitted)
- Be able to provide: tax returns, recent bank statements, and two months of most recent proof of income (examples include paystubs, award letters, child support, social security, disability, unemployment, financial aid, gift letter)
The first four Bethel Homes will be located on Burkhart Road in Howell Township. For these first four homes, the income limit is 60% of Area Median Income (AMI). Future homes may be available to those earning up to 80% of AMI.
Total household income limit (at 60% of AMI) by total household size:
Apply for a Home
Step 1: Review the detailed Homebuyer Guide in “How It Works” as well as “Do I Qualify?”
Make sure you meet the basic eligibility requirements.
Step 2: Complete the Bethel Homes CLT Homeownership Screening Form
Complete the initial screening form and pay the $35 screening fee via the link in the screening form.
What happens next?
Once you have completed the Homeownership Screening Form and paid the required fee, your screening form will be reviewed. Potential homebuyers who appear to meet income guidelines and eligibility requirements will be invited to complete an application and submit all the required documents through an online portal.
Be prepared to provide:
- Two months of recent bank statements
- Two months of income documentation
- Most recent tax return
- Conventional mortgage pre-approval
- Homebuyer education certificate (typically occurs after the application is submitted)
- Pay a $200 commitment fee
If you don't meet all eligibility requirements right away, homeownership may still be within reach—it simply means "not yet." If you aren't currently able to qualify, you will hear from us with the reason why. We encourage you to work on these proactive steps that can help you get program-ready for future opportunities:
Steps to Prepare Your Financial Health
- Work on Credit Health: Lenders review your credit history to determine loan eligibility and interest rates. Review your credit report for accuracy, focus on paying bills on time, and pay down existing debt to raise your score.
- Get Prequalified for a Mortgage: Reach out to a mortgage lender or local bank to request a mortgage prequalification. This helps you understand your homebuying budget and demonstrates financial readiness for a CLT home. Keep in mind that a full pre-approval letter will be required as part of the application process.
- Prepare for the Next Bethel Homes Opportunity: Don't wait until application day to get organized. Gather your income statements, tax forms, and asset documentation now so you are completely prepared to submit a complete application without delay.
Stay Connected & Informed
- Keep Connected: Sign up for updates to get the latest program information and housing site additions.
- Watch "Housing Mamas": Catch weekly video updates on Facebook and YouTube to learn about local housing topics in a fun, quick, and accessible format. Big news is always shared here!
Mortgage Partners
Purchasing a Bethel Homes Community Land Trust (CLT) home is an empowering path to homeownership, but it requires a mortgage provider who understands how land trust financing works. Because CLT properties involve a ground lease structure, working with a lender familiar with the model ensures a smooth, hassle-free approval process.
Financing & Loan Requirements
When applying for a specific home, buyers must be able to secure an approved, long-term financing option through a participating lender.
- Eligible Financing Options: Interested buyers must be able to qualify for a 30-year fixed-rate mortgage.
- Ineligible Loan Programs: Some loans are currently unable to finance land trust homes due to underwriting restrictions regarding leased land.
Working with Mortgage Partners
A lender’s familiarity with ground leases prevents unexpected delays during closing. Our Homebuyer Guide provides a list of our current mortgage partners, complete with the best direct points of contact for CLT buyers.
- Accessing the Partner List: The flyers are from our participating lenders who are willing and interested in working with the Bethel Homes CLT. Contact information is on each flyer. We strongly encourage you to work with one of these lenders.
- Using an Outside Lender: Buyers wishing to work with a lender who is not on the CLT mortgage partner list should share our Homebuyer Guide with their chosen mortgage provider as early as possible so they can review land trust guidelines. Lenders will also need to review all of the detailed CLT documentation, including the Ground Lease and Purchase Agreement. Note: This could be a lengthy process.
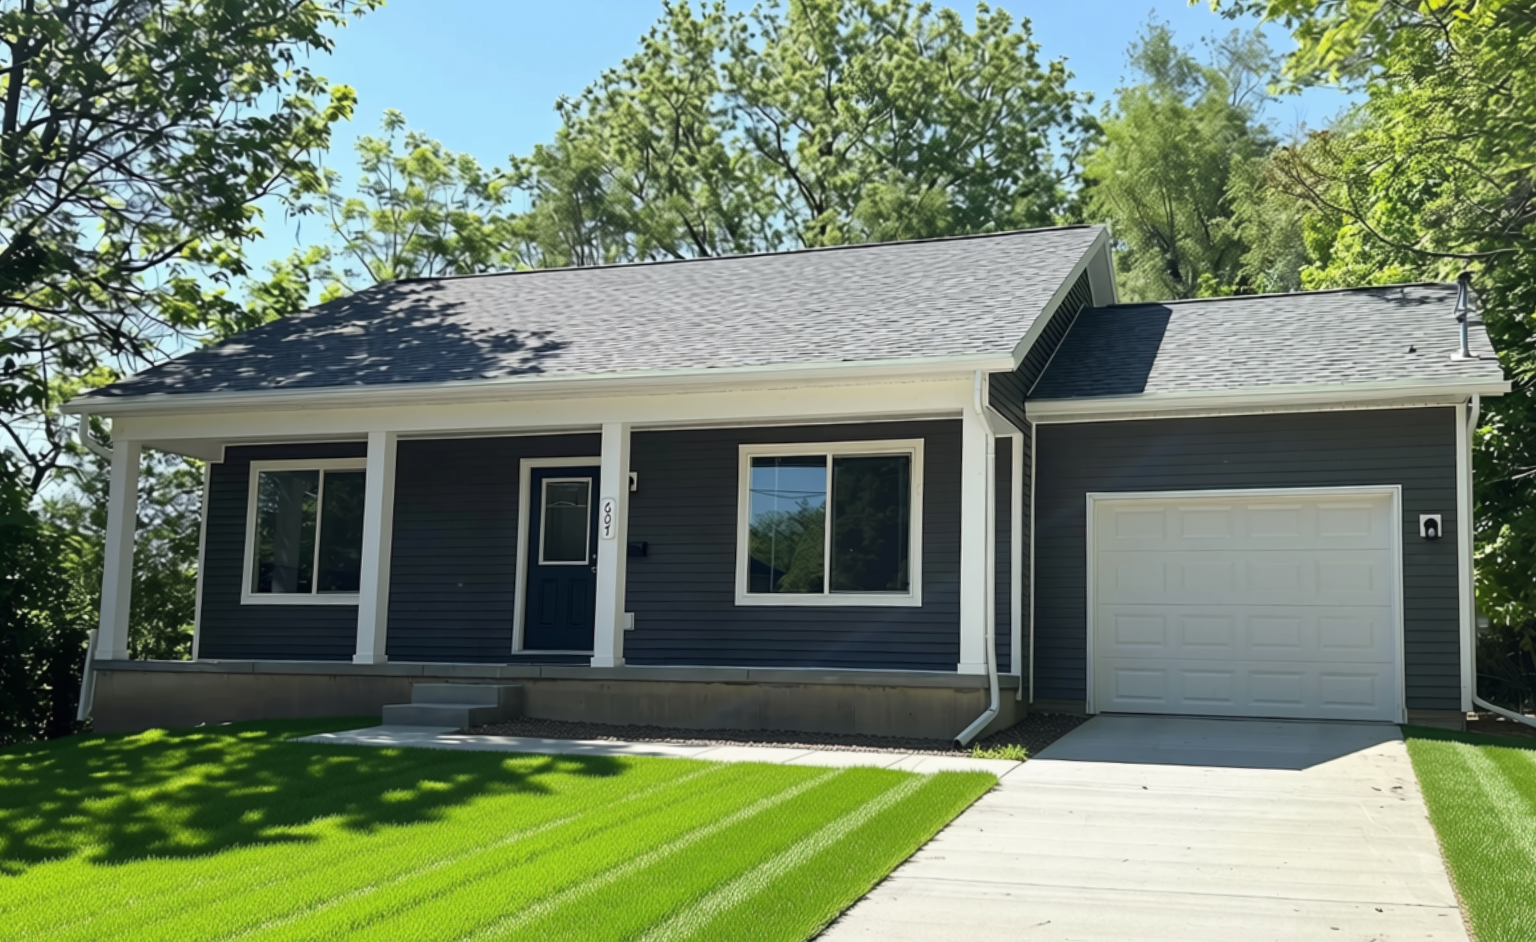
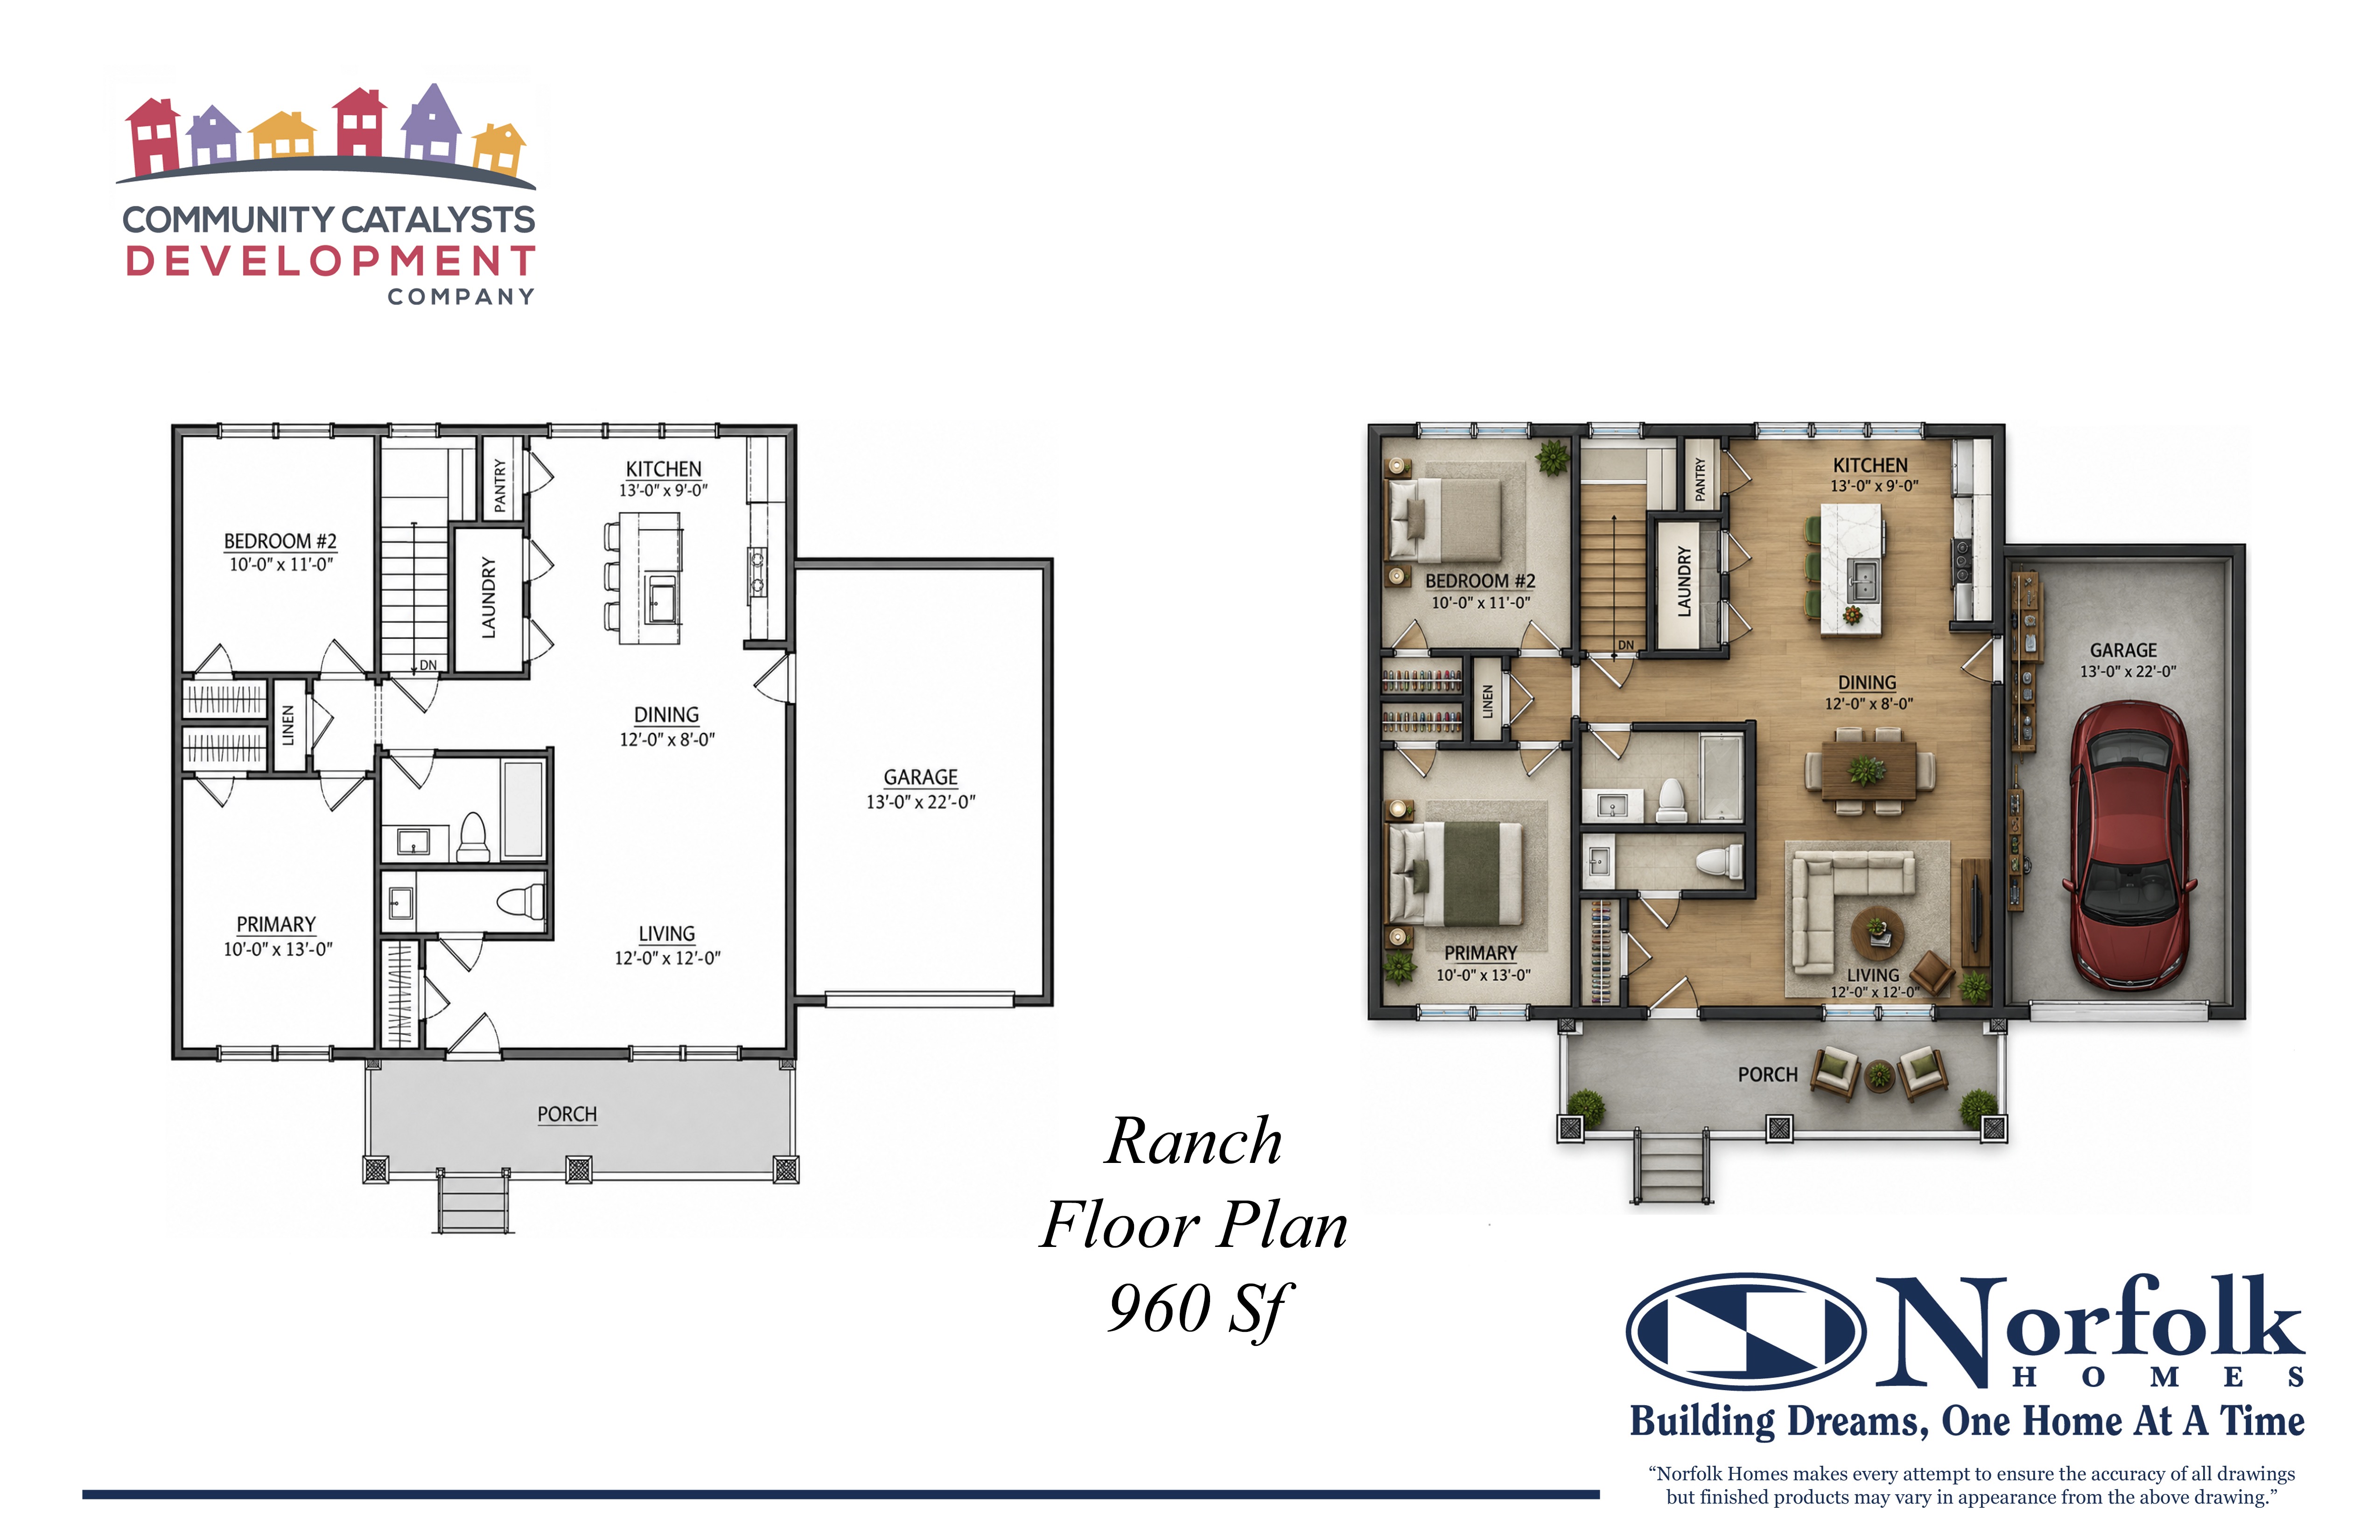
Bethel Homes Floor Plans
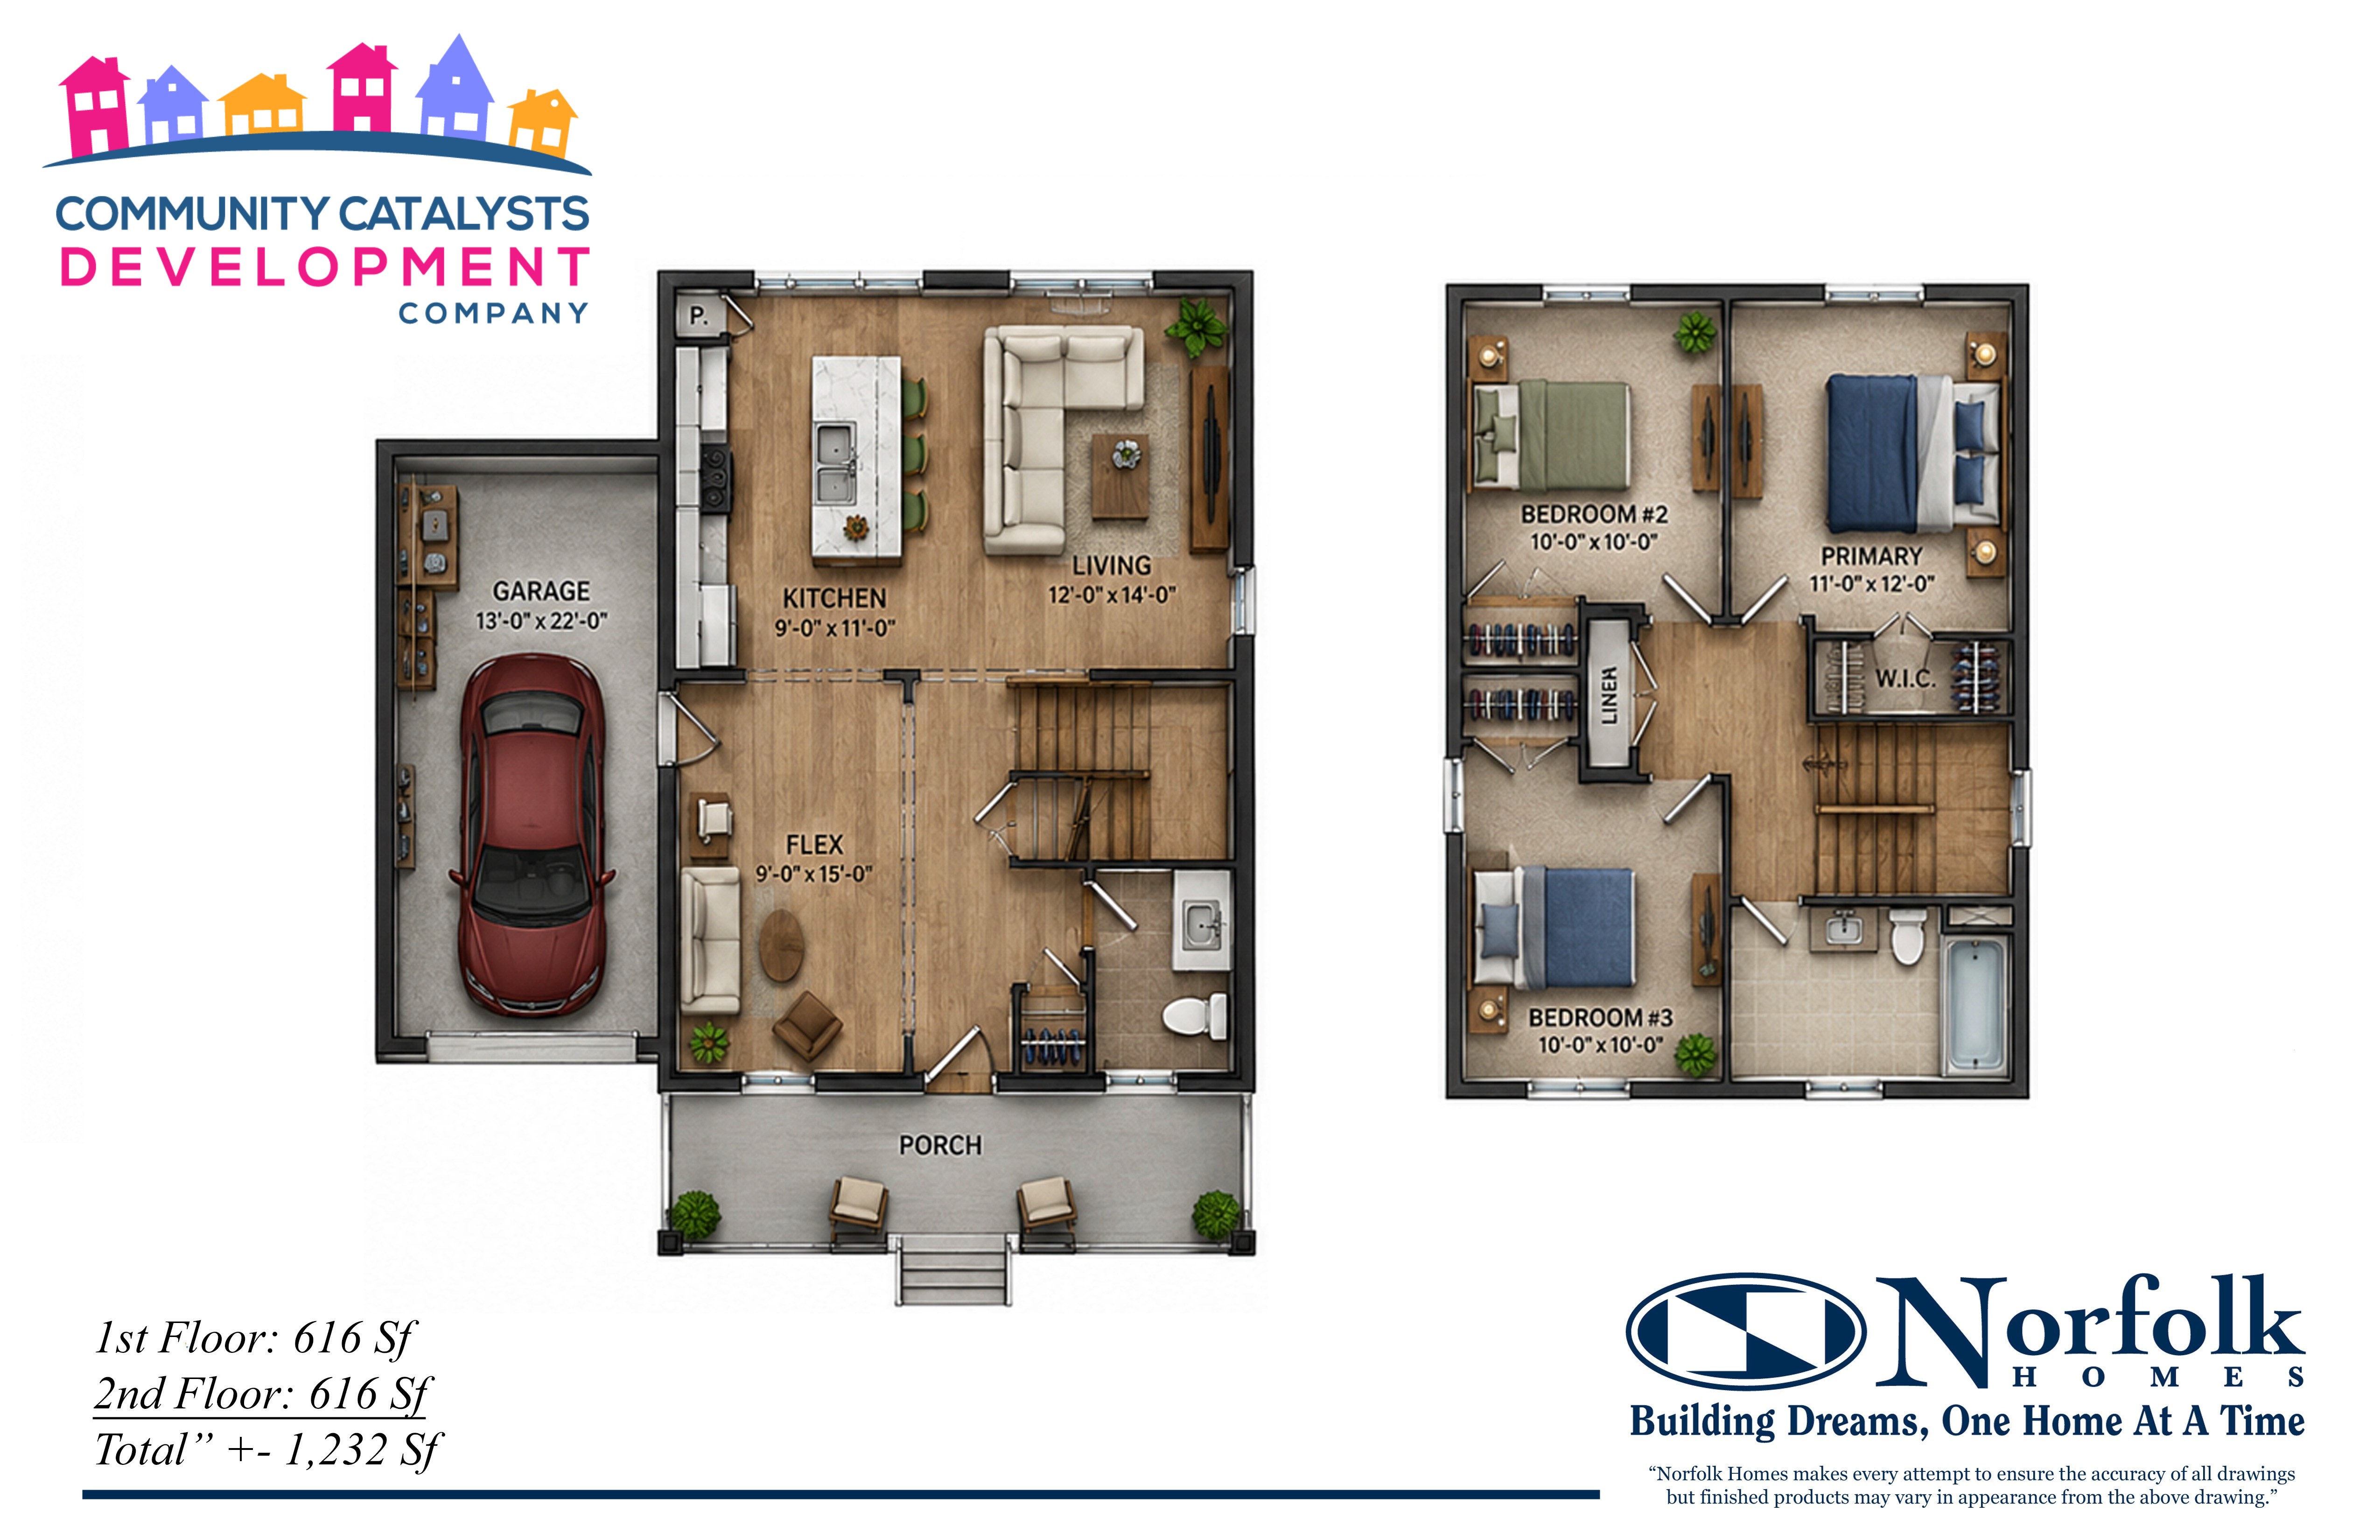
Take the 3D tour
Frequently asked questions
Do I have to live or work in Livingston County to qualify for a home?
Yes, you must either currently reside in Livingston County, work in Livingston County, or have a new contract for employment with an employer who is physically located in Livingston County. "Employment in Livingston County" does not include relocating to the county as a self-employed person.
What does "No Asset Limit" mean?
You may have savings, own a vehicle outright, or have other assets, and still qualify for a home. We encourage all potential homebuyers to save money for a downpayment on a home!
What are debt payments?
Debt payments could include a payment on a car loan, student loan, or credit card payments. They do NOT include things like utilities, rent, or cell phone payments.
Do I have to use one of the mortgage partners on your website?
We highly recommend that you select one of our mortgage partners, as many mortgage providers are not set up to make a loan to a homebuyer purchasing a home through a CLT.
What are the detailed HUD criteria that I need to meet to qualify for a home?
HUD definition of First Time Homebuyer: The U.S. Department of Housing and Urban Development (HUD) defines a first-time homebuyer as an individual who has had no ownership in a principal residence during the 3-year period ending on the date of purchase. This rule also applies to spouses; if one qualifies, the couple is considered first-time buyers.
Under HUD and FHA guidelines, this definition also includes several specific exceptions for those who may have previously owned a home:
- Displaced homemakers: Individuals who only owned a home with a spouse.
- Single parents: Individuals who only owned a property with a former spouse while married.
- Non-permanent foundations: Buyers who have only owned a principal residence not permanently affixed to a permanent foundation (e.g., mobile homes or RVs).
- Non-conforming properties: Buyers who previously owned a dwelling that was not up to local building codes, provided fixing it would cost more than building a new structure.
Do I have to income qualify every year for a home or just once?
You only income-qualify ONE TIME to purchase a Bethel Home. After you close on the purchase of your home, we hope your income continues to increase!
When will other homes be available?
We are working hard to find more sites, and will announce new home locations as they become available.
Be first to know
We'll email you Bethel Homes news and new home opportunities as they become available.
{{ nlMsg }}
By signing up you agree to our Terms and Conditions.